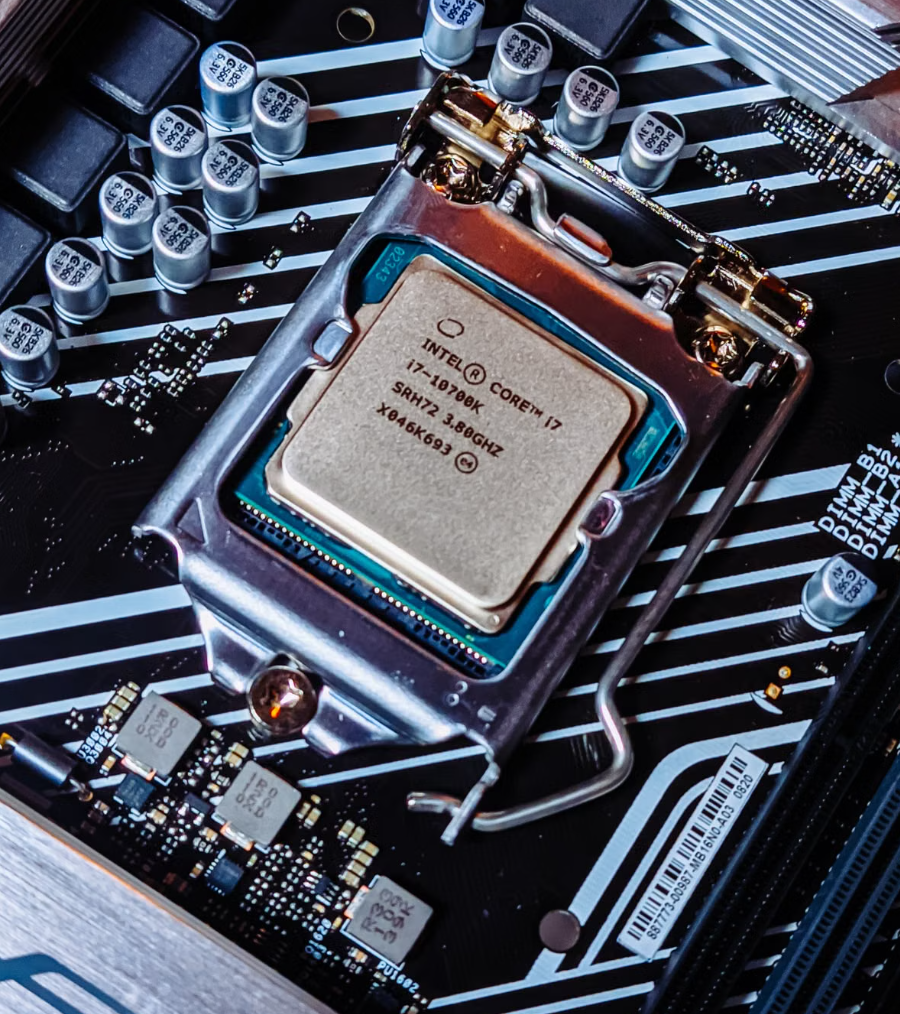
Intel’s Earnings Expose a Growing Problem: AI Demand Is Outpacing Its Ability to Deliver
Intel earnings showed a stronger third quarter, but investors focused on a much weaker outlook for the months ahead. The semiconductor manufacturer reported $16.5 billion in revenue, an increase of 21% from the previous year. However, its forecast for the fourth quarter fell significantly below Wall Street expectations, raising concerns about
manufacturing constraints, slowing PC demand, and the enormous financial burden of expanding production capacity.
Read also: A Pivotal Week for AI Stocks: Hyperscaler Earnings, the Fed and the Midterms — our look at the AI buildout behind the latest Intel earnings.
Shares fell approximately 30% on October 30, wiping out more than $146 billion in market value. The decline reflects a growing concern that Intel may struggle to capitalize on the very AI infrastructure boom that is creating opportunities for other semiconductor companies.
By the numbers
| Financial metric | Reported figure |
|---|---|
| Q3 revenue | $16.5 billion |
| Revenue growth YoY | +21% |
| Adjusted EPS | $0.52 |
| Q3 gross margin | 43.0% |
| Q4 revenue guidance | $15–16 billion |
| Cash at September 30 | $21.84 billion |
| Long-term debt | $46.32 billion |
Investor perspective: What it means for value and risk
The third-quarter results initially appeared encouraging. Adjusted earnings of $0.52 per share exceeded the approximately $0.40 analysts expected, while revenue also narrowly exceeded estimates.
The problem is forward guidance. Intel expects fourth-quarter revenue of $15 billion to $16 billion, compared with approximately $17.08 billion anticipated by analysts. Adjusted earnings guidance of $0.25 per share also fell below the approximately $0.43 consensus estimate.
Bank of America analyst Vivek Arya downgraded Intel from Buy to Neutral and reduced his price target from $145 to $100. His concerns included weakening PC demand and supply constraints offsetting opportunities in data-center processors.
The bullish argument is that Intel still has considerable opportunities in AI-related computing, server processors, and advanced semiconductor manufacturing. Management says demand for its Xeon processors is strong and that increasing supply is a priority.
The bearish argument is that manufacturing investments are consuming significant cash while the company struggles to meet demand. Intel has also indicated that it does not expect positive cash flow for 2026.
(investing.com)
Customer perspective: What it means for buyers
The consequences extend beyond investors.
Businesses building data centers depend on a reliable supply of processors. Intel’s supply constraints could affect the speed at which some customers expand their computing infrastructure.
Meanwhile, consumers purchasing computers face another potential complication: rising memory prices and a softer PC market are increasing pressure across the industry.
For customers, the practical consideration is to compare complete computer configurations rather than focusing exclusively on the processor brand. AMD and other manufacturers remain alternatives worth evaluating.
Intel has acknowledged the supply difficulties and says it is prioritizing increased production to meet customer demand.
Employee perspective: What it means for workers
Intel is also navigating workforce uncertainty while attempting to improve manufacturing efficiency.
California WARN records show several permanent-layoff notices associated with Intel operations in Santa Clara during July and September. One recorded entity reported 91 affected workers across two notices. This is a limited, location-specific figure and should not be interpreted as Intel’s total workforce reduction.
The company’s latest earnings announcement does not provide a comprehensive new global headcount or layoff figure.
(Employees First Labor Law)
The synthesis: Who wins and who bears the cost?
Intel’s situation illustrates the difference between participating in an industry boom and actually benefiting from it.
Data-center customers need more computing capacity, but Intel must overcome manufacturing limitations before fully capitalizing on that demand.
Shareholders are questioning whether the company’s investments will produce sufficient returns. Employees face uncertainty as management attempts to improve efficiency.
What to watch next: Intel’s fourth-quarter results, production capacity, cash-flow performance, and whether its data-center business can grow quickly enough to offset weakness in the PC market.
Primary sources: Intel Q3 2026 earnings release · Intel SEC filing · Reuters market coverage
Note: Investment calculations and projections are for illustrative purposes only and do not constitute investment advice. Please do your own research before making any investment decisions.


