Brazil’s Market Rout Is a Cautionary Tale for U.S. Midterm Investors
Industry overview
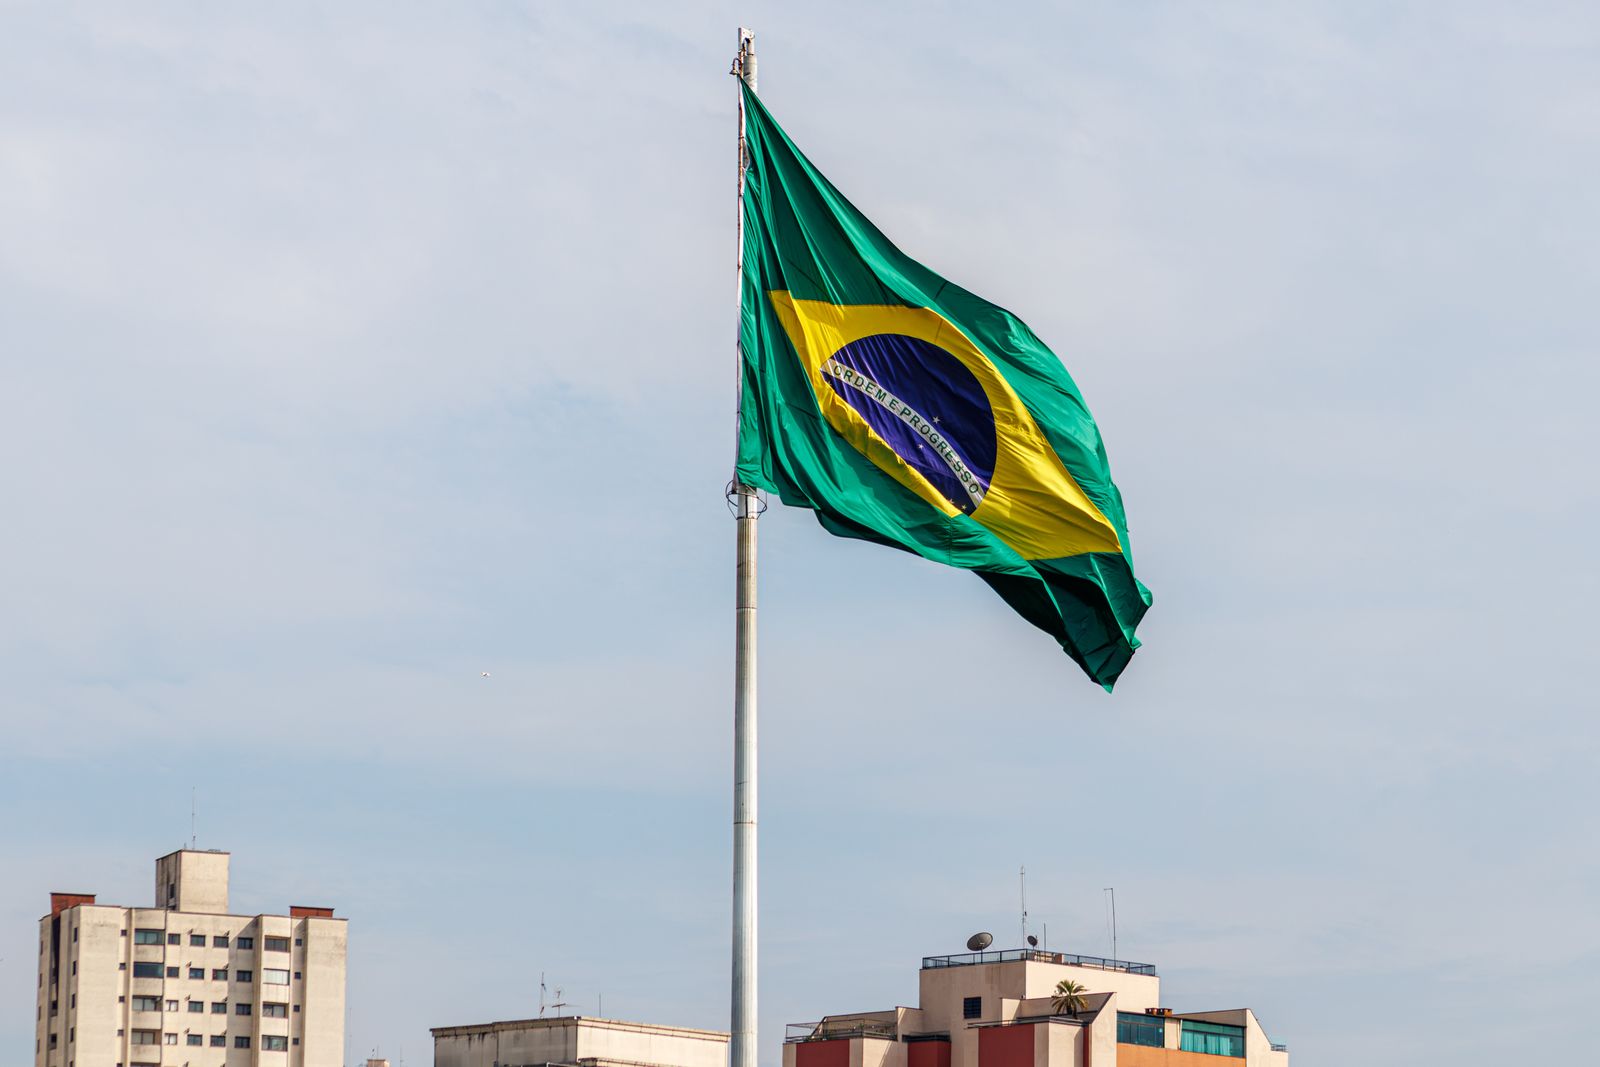
Brazil’s voters returned incumbent President Luiz Inácio Lula da Silva to office in a close Sunday runoff, with about 52% of the vote against Flávio Bolsonaro — a result that caught the market off guard. Bolsonaro had narrowly led Lula after the first round three weeks earlier, and late polls still showed him slightly ahead, so investors had piled into Brazilian assets. The iShares MSCI Brazil ETF (EWZ) jumped 12.5% the day after the first-round vote, its best day since March 2020, and pulled in $4.1 billion of new money over the following three weeks, close to 30% of the fund’s total assets. Those buyers were betting a Bolsonaro win would be friendlier to business, restrain public spending and open the door to lower interest rates.
Instead, Lula won, and he inherits a difficult fiscal picture: Brazil’s public debt has climbed above 82% of GDP, its highest in five years, while interest payments alone now absorb more than 8% of the country’s economic output. Bolsonaro’s Liberal Party also finished as the largest party in both chambers of Congress. Investors worry spending and debt will stay high, keeping interest rates elevated and borrowing costlier for companies and households.
The market’s reaction was sharp as traders unwound their Bolsonaro bets. EWZ fell as much as 27% in premarket trading and was still down roughly 20% in the afternoon; if that decline holds into the close, only one day in the fund’s 26-year history would have been worse, March 16, 2020, when it dropped 23.1%. Nu Holdings Ltd. (NU), one of the world’s largest digital banks and Latin America’s biggest fintech, fell about 18% on fears of tax increases and tighter rules for Brazilian financial firms, while traditional banks did worse still: Itaú Unibanco (ITUB) and Banco Bradesco (BBD) each slid more than 26% before the open. Petróleo Brasileiro S.A. (PBR) held up a little better but still lost 14%, with investors concerned that state control could expose its prices, taxes and dividends to political decisions. MercadoLibre Inc. (MELI), Latin America’s largest online commerce and technology company, declined 9%.
The author, who had recommended PBR the previous week, calls the selloff a buying opportunity, describing Petrobras as an exceptionally strong oil company with an exceptionally strong growth profile, and noting that because it sells oil priced in dollars, a weaker real boosts those revenues once converted into reais.
The piece then steps back to a wider lesson: charged political labels such as “socialist” and “populist” can distort reality. Lula’s critics use both terms with some justification, the author says, but Lula has also chosen pragmatism over ideology when it mattered. The same pattern played out in October 2002, when Brazilian markets collapsed and the real sank to record lows on fears Lula would win his first presidency — only for Lula to install an orthodox finance team, after which investors spent years unwinding the “Lula discount.” The Bovespa Index rose nearly 1,200% in U.S.-dollar terms during Lula’s first two terms, from 2003 through 2010, helped by a global commodity boom and a real that roughly doubled against the dollar, and Brazilian stocks have also gained during his current term even after the latest selloff. By contrast, the Bovespa lost about 7% in dollar terms across the four years of Lula’s “business-friendly” predecessor, Jair Bolsonaro — the father of the candidate who lost on Sunday — with the pandemic sharing some of the blame.
Markets, the author argues, often fixate on narratives rather than substance, and the current selloff looks like an overreaction and a buying opportunity. A Bolsonaro win might have made the day more pleasant for holders of Brazilian stocks, but the following year might not have been. Center-right parties will hold roughly 57% of the lower house and 62% of the Senate, a map that could slow the spending reforms investors want but also sets a firm limit on populist excess. The author expects the pragmatic Lula to dominate over the next four years.
The broader point is that markets do not react to whether news is good or bad, but to the gap between what happens and what investors expected, and a portfolio built around a single anticipated outcome can unravel in one session when that outcome never arrives. A similar risk hangs over the U.S. market ahead of next week’s midterm elections, where political shifts can move sentiment but the greater danger is overcommitting to one popular market narrative. The best investment opportunities, the author writes, can appear when expectations collide with reality — and one may be forming in the AI market ahead of America’s midterms.
The article closes by looking ahead: Microsoft Corp. (MSFT), Alphabet Inc. (GOOGL), Meta Platforms Inc. (META) and Amazon.com Inc. (AMZN) all report earnings in the week before the election, and the author expects them to lift their 2027 spending plans again, as they have nearly every quarter for two years, taking their combined planned AI spending to about $1.3 trillion. Then America votes: 36 states will elect governors, most state legislatures and thousands of local officials are on the ballot, and nine states will choose utility regulators who help decide who pays for power. The morning after the election, Wall Street could face $1.3 trillion of planned AI spending alongside newly elected officials pressing AI companies to shoulder more of the costs — pressure on the companies building the AI boom just as investors question what those investments will return. The author points readers to a free special presentation on what to watch ahead of the midterms and where the next AI opportunities may emerge, noting the publisher is taking it down at midnight tomorrow.
The piece also recaps the previous week’s Smart Money articles: on October 21, 2026, “Stop Looking at Who Builds AI – Look at Who Puts It to Work,” on how the companies that use AI infrastructure often profit more than those that build it; on October 22, “As the Market’s Party Shrinks, Here’s One Stock to Buy,” comparing the market to a cocktail party and naming an overlooked healthcare stock; on October 24, “As the AI Buildout Slows Down, Here’s What to Do Next,” on positioning for the next phase of the AI trade as data center projects face delays, permitting hurdles and rising costs; and on October 25, “Anthropic Could Be the Next Amazon, and That’s the Problem,” on why even the next Amazon can be a poor investment at a rumored valuation.
Industry overview based on InvestorPlace.
What it means for investors
The core lesson here is about positioning, not politics. The EWZ trade shows how quickly a crowded, one-sided bet can reverse: $4.1 billion flowed in on the expectation of a Bolsonaro win, and a single surprise result turned that into a 20% drawdown in a day. Investors who sized the position as a speculation can live with that; investors who treated it as a sure thing cannot. The same discipline applies to the U.S. midterms and the AI trade. Four companies are about to tell the market they plan to spend roughly $1.3 trillion, and the market has spent two years rewarding that spending. If the post-election landscape starts asking who pays for the power and infrastructure behind AI, the stocks that have benefited most from the build-out are the ones with the most to lose, while the companies that put AI to work — the users rather than the builders — may be where the next gains are found.
On Brazil itself, the selloff has created a genuine valuation question rather than a reason to panic. Petrobras still sells dollar-priced oil, so a weaker real works in its favor, and the author’s case for buying PBR into the drop rests on that cash-flow resilience. But the fiscal backdrop is real: debt above 82% of GDP and interest eating more than 8% of output will keep Brazilian rates high, which argues for selectivity. The sharp split between the old-line banks, down more than 26%, and MercadoLibre, down 9%, is a reminder that within the same country, business models matter more than the flag. For investors holding EWZ or Brazilian names, the sensible move is to re-underwrite each holding on its own earnings power rather than on the election narrative that just failed.
What it means for employees
For workers at Brazil’s banks and fintech companies, the election result brings a period of uncertainty rather than immediate change. The market’s fear of higher taxes and tighter regulation of financial firms has not yet become policy, but it puts hiring and pay decisions at Nu, Itaú and Bradesco under a cloud until Lula’s fiscal plans become clear. At Petrobras, employees of a state-controlled company face a different dynamic: political influence over pricing, taxes and dividends can change strategy from the top, which affects everything from investment plans to job security in the field. On the U.S. side, the AI spending wave remains a powerful source of jobs in data centers, engineering and cloud work, but if the post-midterm debate shifts costs onto the builders, the pace of that hiring could slow, and the winners may be the companies applying AI rather than those constructing the infrastructure.
What it means for customers
For Brazilian customers, the immediate impact is indirect but real. If high government debt keeps interest rates elevated, borrowing gets more expensive — costlier credit cards, auto loans and mortgages for households, and pricier financing for small businesses. Petrobras customers could eventually feel political decisions in fuel pricing, though that depends on policy choices that have not been made yet. For shoppers on MercadoLibre, the selloff is a market story for now, not a change in the service they use day to day. In the U.S., the customer angle sits with the nine states electing utility regulators: those officials help decide who pays for the power that AI data centers consume, so the election could eventually show up in household electricity bills, while the big tech platforms’ AI features keep arriving regardless of which way the market moves.
Note: Investment calculations and projections are for illustrative purposes only. Market conditions change frequently. Consult a qualified financial advisor before making investment decisions.


